A balance sheet is a photograph of what a company owns and owes on one particular day.
It is not a story about how the year went. That's the income statement. Knowing which document answers which question saves an enormous amount of confusion.
Most people open a balance sheet and immediately close it again. But once you know what matters, it becomes shockingly simple.
The four numbers
Cash. The lifeline. Near the top of the assets. Cash is the company's oxygen. No oxygen, no business — just a very expensive corporate corpse, and not something you want in your portfolio.
Debt. The trouble meter. Add the short-term and long-term borrowings, then compare them to cash. A company holding more cash than debt is in a fundamentally different position from one holding four times more debt than cash.
Current assets and current liabilities. The things turning into cash within a year, and the bills due within a year. If the bills are larger than the incoming cash, the company has a squeeze coming.
Shareholders' equity. Assets minus liabilities. Roughly, what would be left for owners if everything were settled today. Watch whether it grows over the years or shrinks.
The good news: you don't have to add anything up
Everything above is real, and if you enjoy digging through filings, go and dig.
But you don't have to. Two of those four numbers get turned into ratios that do the comparing for you, and both sit on the same page as the stock quote within our website.
The current ratio is current assets divided by current liabilities. Above 1 (thst's good) means more is coming in than going out over the next year. Below 1 (and that's bad) means the squeeze or paying bills is going to get difficult.
Total debt to equity is exactly what it sounds like. 0.30 means thirty cents of debt for every dollar owners have in the business. 5.00 means five dollars of debt for every dollar.
Here is Nvidia, on 3 August.
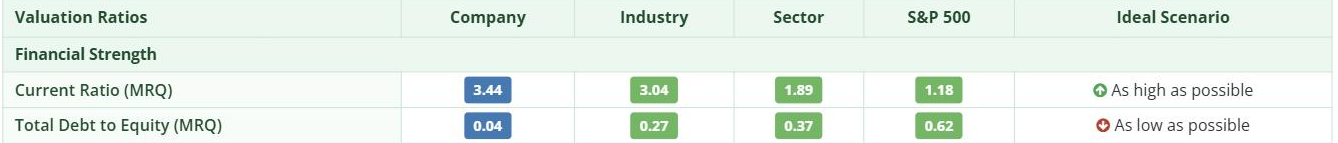
A current ratio of 3.44 — more than three dollars coming in for every dollar due. And four cents of debt for every dollar of equity.
Now the same two rows for Norwegian Cruise Line, on the same evening.
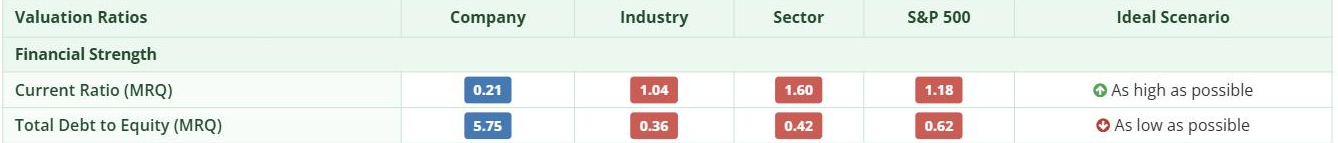
A current ratio of 0.21. Twenty-one cents coming in for every dollar due inside the year.
And $5.75 of debt for every dollar of equity.
Those are two different worlds, and it took about ten seconds to see it.
Why the comparison columns are the point
Here is the trap almost every beginner falls into: they learn that a current ratio above 2 is "good," go and check one company, and stop there.
But 0.21 for a cruise line and 0.21 for a software company mean different things. Cruise lines own enormous, expensive ships, and those ships are financed. Heavy debt is normal in that business. It is not normal in semiconductors. Just like comparing your house to a completely different home in a different neighborhood. It doesn't make any sense. You compare your home to comparable homes in your same neighborhood and the same applies to stocks and their industry.
That's why the Industry, Sector and S&P 500 columns sit right beside the company's own number. You're never asked to know from memory whether 0.21 is alarming. You can see that its own industry averages 1.04, and draw your own conclusion.
The colour coding is doing the same job. It isn't telling you to buy or sell anything. It's telling you which side of the average the company landed on.
The one question
Ask this: if this company had a genuinely bad eighteen months, would it survive without having to raise money on bad terms?
Cash, debt and the current ratio are how you answer it.
That single question filters out an enormous amount of trouble before you ever look at a chart.
And notice it is not the same as asking whether the stock goes up. A heavily indebted company can be a wonderful investment, and a cash-rich one can go nowhere for years. What the balance sheet tells you is how much room the business has to be wrong.
What trips people up
Goodwill. Goodwill is what happens when a company overpays for another company because someone got a little too excited in the boardroom. The difference gets recorded as goodwill on the balance sheet.
It is a real accounting entry. But it is not cash, and it cannot pay a bill.
A balance sheet that looks strong mostly because of a large goodwill figure deserves a second look.
Why this matters to you personally
Most of the investments that hurt people badly were not businesses that grew slowly.
They were businesses that ran out of room. Too much debt, not enough cash, a bad stretch at the wrong moment.
Ten minutes with a balance sheet is the cheapest insurance available to you, and it costs nothing but the habit.
What to take away
- Balance sheet = one day. Income statement = one period. Different questions.
- Cash versus total debt is the fastest read on staying in business or going out of business.
- Current assets smaller than current liabilities means a money squeeze is coming.
- A ratio only means something next to its industry. 0.21 for a cruise line is not 0.21 for a chipmaker.
- Goodwill is real accounting, but it cannot pay a bill.
How much room does this business have to be wrong?
Now go do it on something you own
Ten minutes, and you'll never look at a holding the same way again.
- Pull up a company you own and scroll to Financial Strength.
- Write down the current ratio and the debt-to-equity, and the industry number beside each.
- Is the company on the comfortable side of its own industry, or the tight side?
- Then ask the question: could it survive a bad eighteen months?
$0.99 for 14 days, then $24.99/month. Cancel online anytime.
Figures captured on 3 August 2026 and they have moved since. Nvidia and Norwegian Cruise Line appear here because they sit at opposite ends of the same two measurements, which makes the comparison easy to see — nothing above is a view on whether you should own either one. A strong balance sheet is not a prediction, and a stretched one is not a verdict.
A lesson, not advice. Companies named are teaching examples, not recommendations. Investing involves risk, including the loss of the money you invest. Full disclosures.